Spokane Valley · Licensed in WA & ID
Know exactly what you can buy. Before you write the offer.
Dave Lesser · Lesser Lending · Spokane, WA & Idaho
Most buyers find out what they qualify for and stop there. We go further: what it costs, how to structure it, and what makes your offer stronger than the one next to it.
Takes about 12 minutes. No credit pull until you say go.
Loan Strategy Center
Run the numbers yourself.
Ten tools built around the decisions buyers and agents actually have to make. No login, no credit pull, and no lead form standing in front of the answer.
Home Buying Game Plan
Answer questions about your timeline, savings, and credit. We map which programs are worth looking at and what is actually standing in your way.
Down Payment Assistance
Enter price, income, and what you have saved. See roughly where you would land out of pocket once assistance and a seller credit are working.
Buy vs. Rent
Put in what you pay in rent and a target price. Compare it against an estimated payment with assistance and seller credits factored in.
Can You Afford This House?
Price, income, monthly debts, savings. Returns the payment, your debt-to-income, what is left in the bank after closing, and which programs fit.
VA Eligibility Check
A few questions about your service and the property. Shows what applies to your situation and what your Certificate of Eligibility still has to confirm.
Start Your Pre-Approval
The full picture — credit, income, timeline, agent, location. Goes straight to a loan officer for a real review, not an automated letter.
Payment Calculator
Pick a loan type and the rate and mortgage insurance adjust with it. Taxes, escrow, amortization schedule, and a cash-to-close range.
Can We Beat Your Rate Offer?
Enter the rate and points you were quoted. We break down what those points actually cost and where the real difference between offers hides.
Should You Refinance?
Your current rate, balance, and home value. Returns the break-even in months — the number most refinance pitches leave out.
Market Rates
Eleven national averages updated daily, with a chart running back decades. Useful for context, useless for knowing what you would actually pay.
Every tool has its own page, so you can text one straight to a client or drop it in an offer email.
Browse the Loan Strategy Center →Payment estimate
What would that actually cost per month?
Pick a loan type and the rate and mortgage insurance adjust with it. Want the full picture — taxes, escrow, amortization, cash to close? Open the full calculator.
 Payment Calculator
The rate is an assumption you control, not a quote. National average index shown by default.
Estimated monthly payment
Calculators are self-help tools. All examples are hypothetical and are for illustrative use only. Not a quote, rate lock, approval, or commitment to lend. Assumes a 30-year term. All loans subject to credit and property approval.
Loan programs
The program is a strategy decision, not a default.
Most buyers get handed whatever the lender runs most often. The right answer depends on your cash, your credit, your timeline, and what you're trying to negotiate.
Down payment assistance is the most misunderstood money in the market.
Most buyers assume it means a worse rate, a slower close, or a program they'd never qualify for. Usually none of that is true. Washington runs WSHFC. Idaho runs through IHFA. Both can layer with a seller credit, and in a lot of scenarios that combination potentially puts a buyer into a home for roughly a thousand dollars or less out of pocket.
Income and purchase price limits apply, and they're different in every state and often every county. Which is exactly why most lenders quote you a conventional loan and never bring it up.
See what you'd qualify for3% down is real
HomeReady and Home Possible open the door well below 20%, and mortgage insurance comes off later. Twenty percent down is not automatically the smarter move.
Not a bad-credit loan
3.5% down, flexible ratios, and it's assumable — which matters more in a higher-rate market than most agents realize.
Zero down, no monthly MI
The strongest financing available to anyone who earned it. We'll also call the listing agent so your offer doesn't get passed over on a myth.
Zero down outside city limits
The eligible map covers more of eastern Washington than buyers expect. Worth checking before you rule it out.
When the box doesn't fit
Self-employed, bank statement, DSCR, ITIN, physician. A complicated file isn't a no — it's a different program.
Only when the math works
Cash-out, rate-and-term, VA IRRRL. If it doesn't clearly help you, we'll tell you to leave it alone.
Market rates
What the market is doing. Not what you'd get.
National average index figures, updated daily. These are not our pricing and not a quote — your rate depends on credit, program, down payment, occupancy, property, loan amount, and lock period.
Eleven products, updated daily
Conventional, ARM, FHA, VA, USDA, and jumbo national averages, with a chart going back decades. Useful for context, useless for knowing what you'd actually pay.
Rates subject to change without notice. Averages shown are third-party national index figures provided for general market context only. They are not an offer or commitment to lend, and individual rates will differ. All loans subject to credit and property approval.
Our process
Go shopping in four steps.
No guesswork, no overwhelm. Just a clear path to being the buyer a seller takes seriously.
Book a call
Fifteen minutes, before you fill anything out. We get to know your cash, your income, your credit, and what you're actually trying to do.
Application
About twelve minutes, guided the whole way so nothing feels overwhelming. Soft credit pull only, one score per person.
Approval
Finally, the numbers you've been trying to get a straight answer on. What you qualify for, what it costs, and what your real options are.
Go shopping
With actual direction instead of a max price. You'll know what to offer, what to ask the seller for, and what the payment looks like before you write anything.
And we don't disappear once you're out looking. Offers, listing agents, negotiation, contract to close — we're in all of it.
Closings run anywhere from 10 to 45 days. Every file is different, and anyone who gives you a timeline before reading yours is guessing. We'll read yours and tell you what's actually realistic — then hit it.
Ask about your timelineThe whole thing, start to finish.
Every stage from the first call to the day you get keys — who you'll work with, what's expected of you, and roughly how long each part takes. Including the parts other lenders don't explain.
Reviews
Don't take our word for it. Take theirs.
Reviews are submitted by clients and reflect their individual experience. Individual results vary and are not a guarantee of future outcomes or loan approval.
Refer a friend
Know someone who should stop guessing?
Send them our way and we'll take care of them. You'll hear back on where it landed, so you're never left wondering whether it went anywhere.
The team
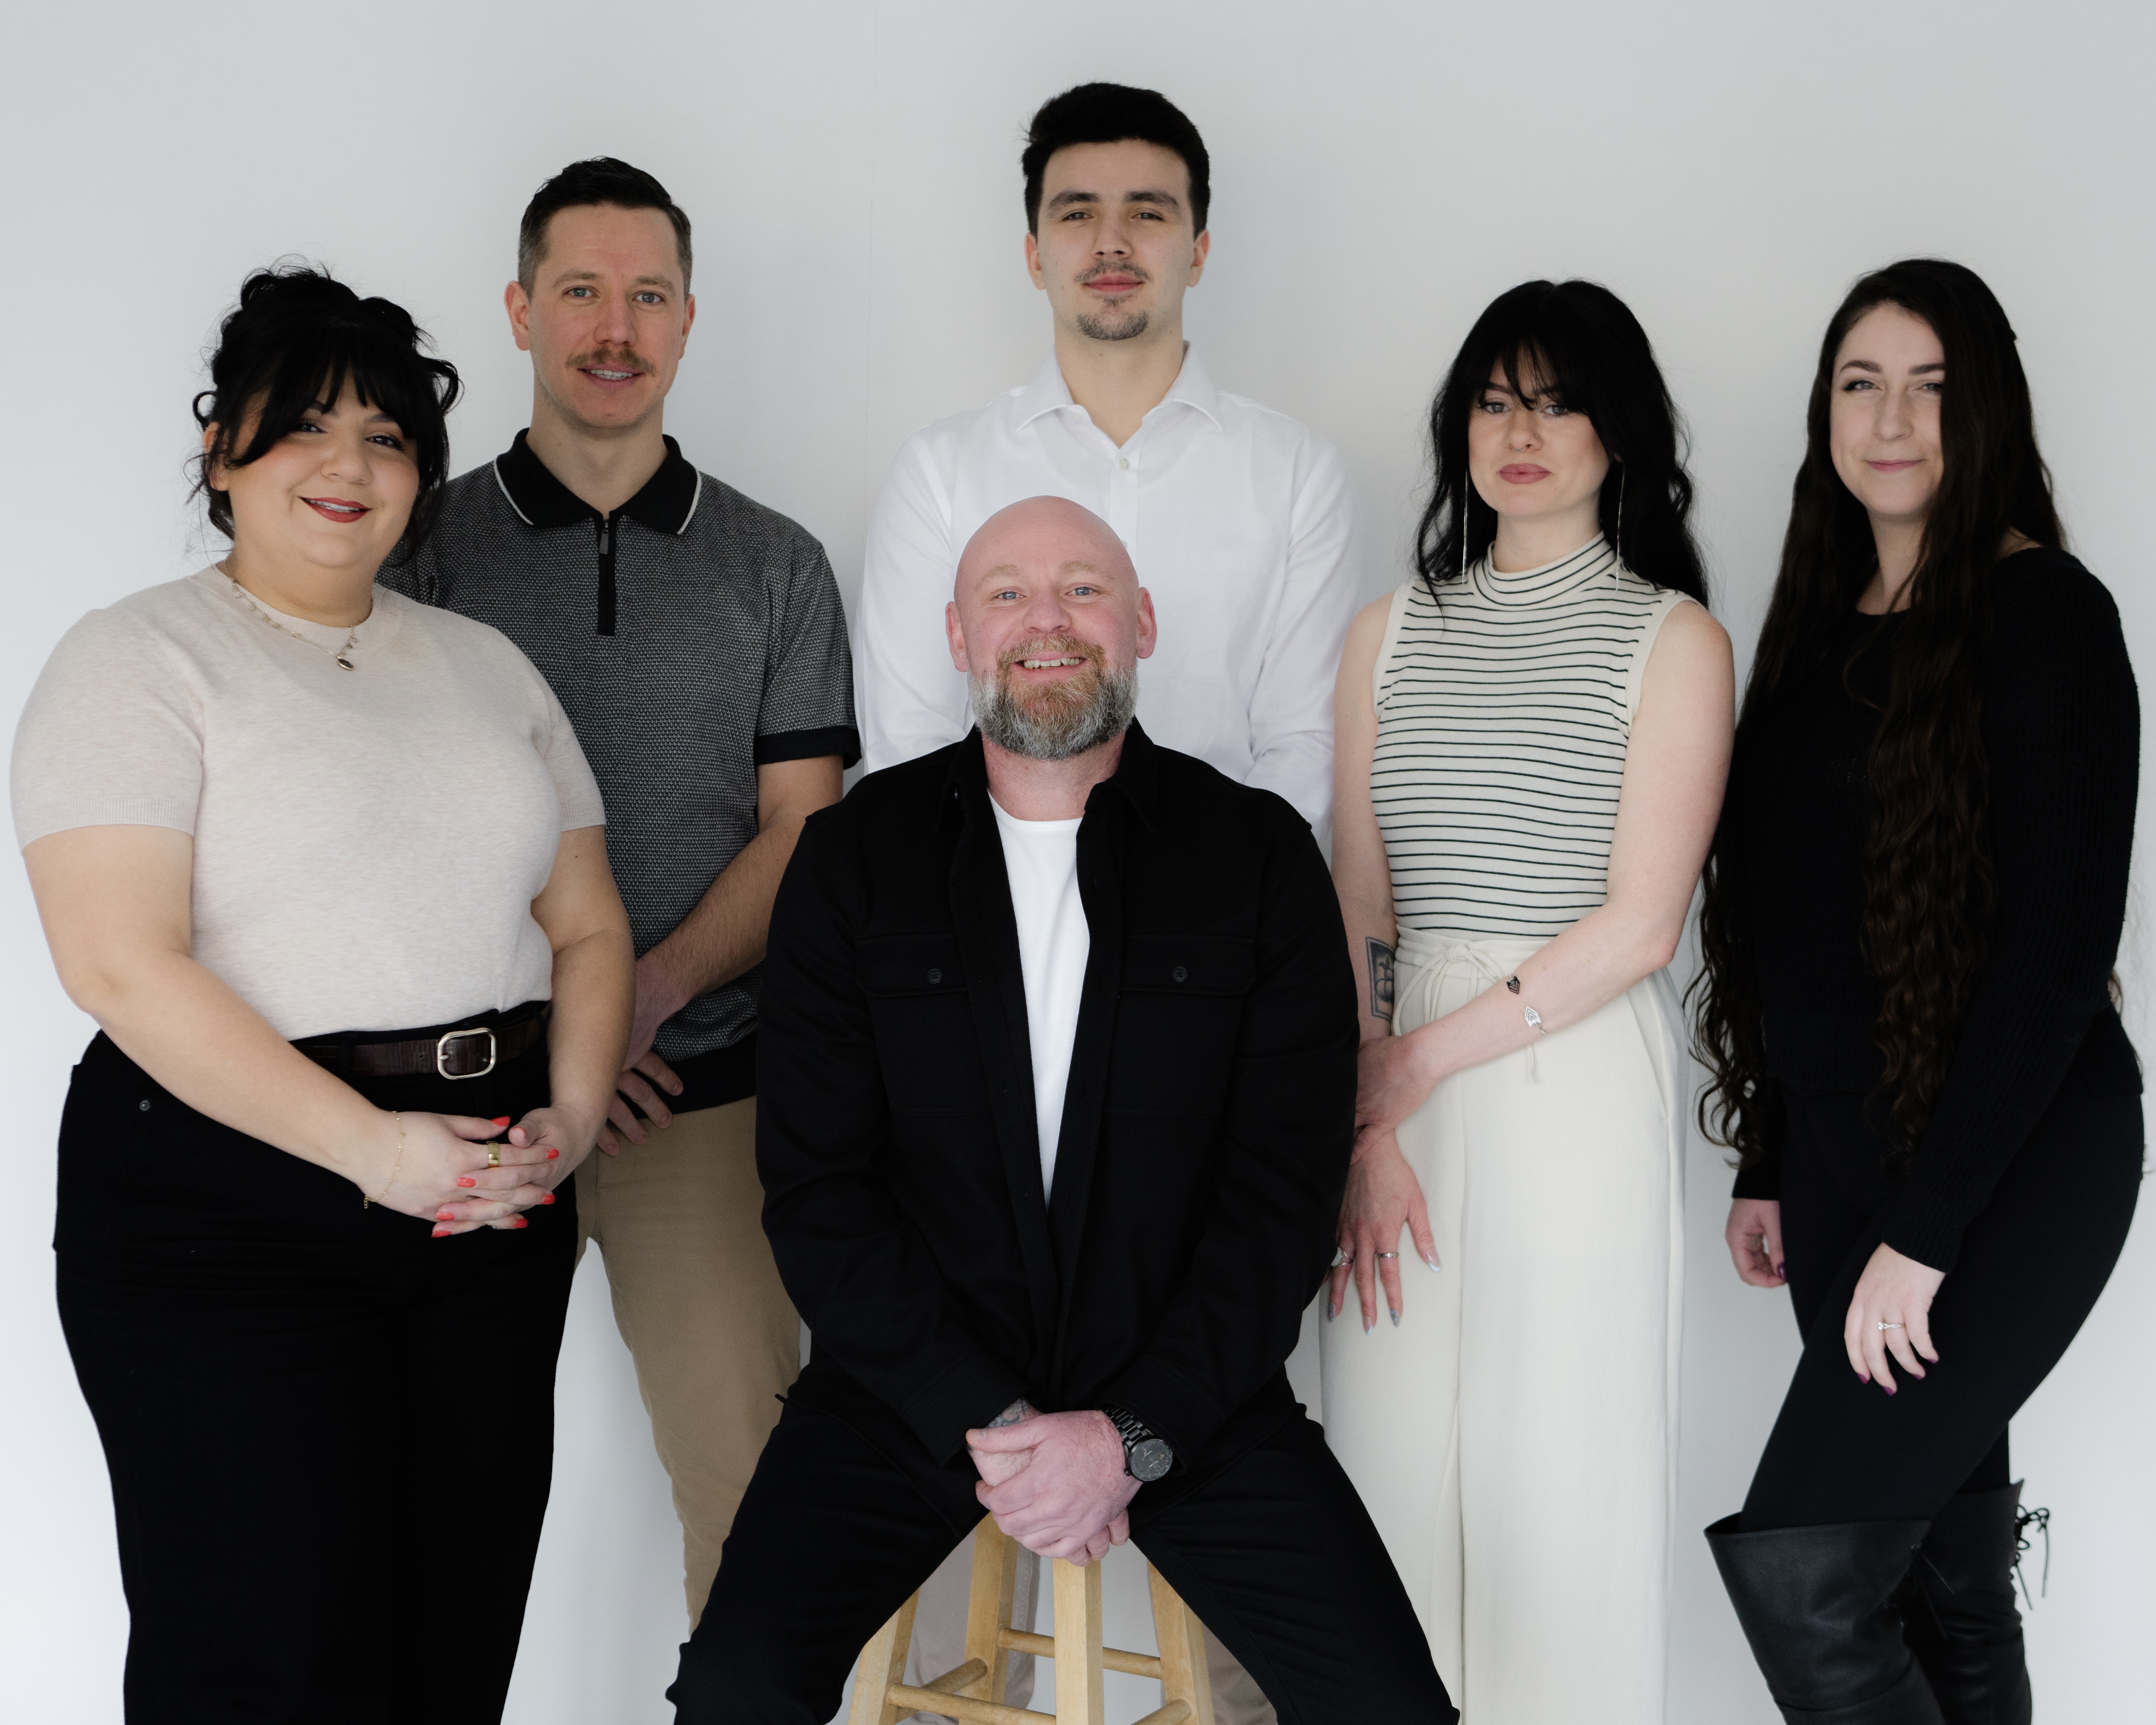
A whole operation, not one guy with a phone.
Dave Lesser is a senior loan officer and sales manager with Canopy Mortgage, ranked in roughly the top 1% of originators nationally and working with buyers across Spokane, Spokane Valley and north Idaho. But you're not buying one person's memory. You're getting a team where everyone knows their role and nothing sits in someone's inbox over the weekend.
For real estate agents
We're not asking to be your number one.
If you already have a lender you trust, keep them. But if you've ever needed a second option on a Saturday, or a file someone else turned down, that's a reasonable place to start.
- Pre-approvals over the weekend, not Monday morning
- We call the listing agent on your offers
- Weekly status updates without you chasing them
- Buyer leads we generate and hand to partners
- Financing education your clients will actually sit through
Try us on one file.
Send the deal you think is going to be a problem. That's the honest test.
Common questions
The things people ask before they call.
Who is Dave Lesser?
Dave Lesser is a senior loan officer and sales manager at Lesser Lending, Div. of Canopy Mortgage, LLC, based in Spokane Valley, Washington. He is licensed in Washington and Idaho under NMLS #189561, has been named a Top 1% Loan Officer nationwide by Scotsman Guide, and manages Canopy Mortgage's highest-producing branch. He is also an Army veteran.
Where is Lesser Lending, and what areas do you lend in?
Our branch is at 11917 E Broadway Ave, Suite 201 in Spokane Valley, WA 99206. We're licensed in Washington and Idaho, so we work with buyers across Spokane, Spokane Valley, Liberty Lake, Cheney, Coeur d'Alene, Post Falls and the surrounding areas.
Can you buy a house in Spokane with little or no money down?
Often, yes. VA loans are zero down for eligible veterans. USDA is zero down on qualifying rural properties. And Washington's WSHFC programs offer down payment assistance that, combined with seller credits, can potentially leave a buyer with very little out of pocket in a lot of scenarios.
Program availability depends on income and purchase price limits that vary by county, so the honest answer is that it takes a conversation to know which of these applies to you.
What credit score do you need to buy a house?
FHA financing generally starts around a 580 score, and conventional around 620. But the score is only one input. Debt-to-income, how long you've been at your job, and what's actually on the report matter just as much.
If your score isn't there yet, that's worth knowing now rather than in April. We'll tell you what's holding it down and roughly how long it takes to fix.
How long does it take to close?
We commonly close purchases in about 25 to 30 days when the file and the transaction support it. The biggest variable isn't us — it's how fast documents come back. Files that close on time are files where requests get answered the same day.
Does a pre-approval cost anything, or affect my credit?
No charge, and the initial review is a soft credit pull that doesn't affect your score. You pay us nothing unless a loan actually closes.
A pre-approval also isn't a commitment. Plenty of people get pre-approved to understand their position and then wait six months. That's a completely reasonable thing to do.
Start with a real number.
Lesser Lending · Spokane Valley, WA · NMLS #189561
The application takes about 12 minutes. Or skip it and just talk to Dave first — that works too.